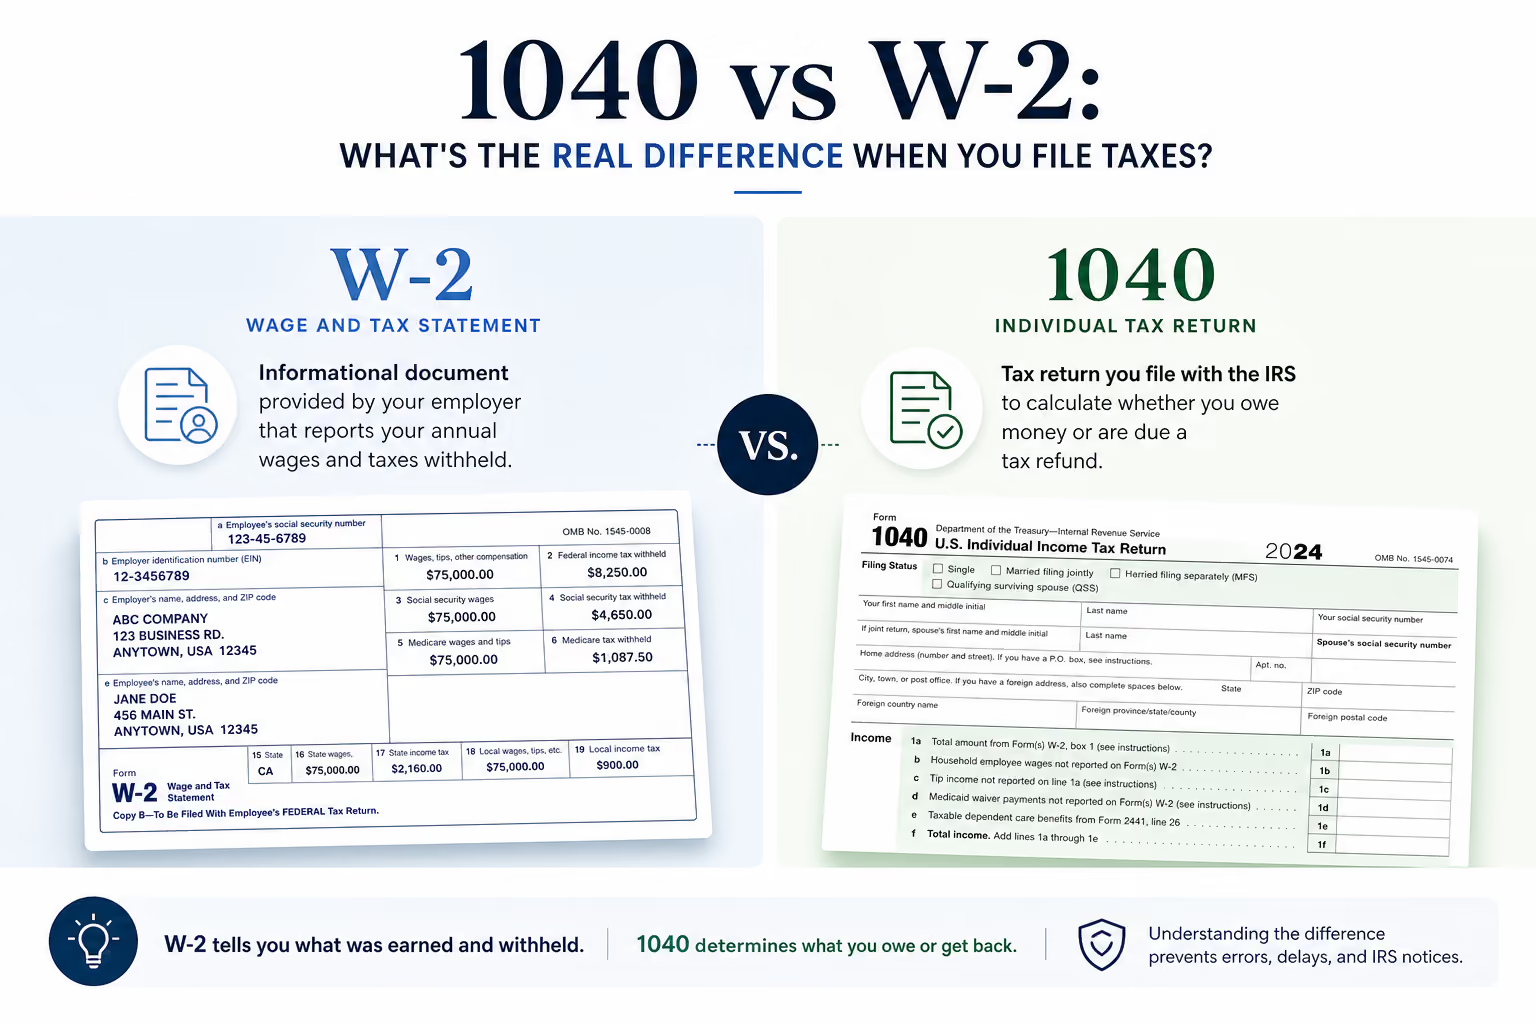
Every tax season, two forms dominate the conversation for U.S. employees: Form W-2 and Form 1040. One is a wage and tax statement your employer sends you; the other is your actual tax return. Confusing the two causes mismatches, delayed refunds, and IRS notices that could have been avoided entirely.
Form 1040 is the primary form U.S. individual taxpayers use to file an annual federal tax return. Almost everyone who must file taxes uses some version of it. Form 1040 is used to report annual income to the IRS and calculate your total tax liability.
The form aggregates all income types: wages from W-2s, interest, dividends, capital gains, business income, Social Security benefits, pensions, and investment income. It then applies adjustments, deductions (standard or itemized), and tax credits to arrive at a final figure showing how much tax you owe or how much your tax refund will be. Form 1040 allows taxpayers to claim deductions and credits, and includes various schedules for additional income reporting, such as Schedule C for self-employed individuals or Schedule D for capital gains.
Who must file? Individuals earning above a certain threshold must file Form 1040. For tax year 2025, a single filer under 65 must file if gross income reaches $15,750. Married filing jointly (both under 65): $31,500. Married filing separately: just $5. Self-employed taxpayers with net earnings of $400 or more must also file. Form 1040 is an IRS form available on irs.gov, and can be filed as a paper return or submitted as a tax return electronically. Incomplete or incorrect 1040s are a common trigger for an IRS notice.
While Form 1040 is the base form, the IRS introduced several variants for specific situations. Selecting the right one matters for accuracy and tax compliance.
Estates and trusts file Form 1041, which falls outside the 1040 vs W-2 comparison for individual taxpayers. VJM Global – USA often advises nonresident individuals and cross-border workers on whether they should file Form 1040 or Form 1040-NR as part of broader cross-border tax planning strategies.
Form W-2, officially the Wage and Tax Statement, is the annual summary of wages and taxes withheld that employers must send to each employee. Form W-2 is an informational document provided by your employer; it is not just one form but a multi-copy document. W-2 forms are sent to the IRS and state tax authorities, and a copy goes to the Social Security Administration.
You receive a separate Form W-2 for each employer during the tax year. Each W-2 form reports wages and tax withholdings for that specific employment relationship. The essential tax document includes these key boxes:
Box
What It Reports
Box 1
Total wages, tips, and other compensation (taxable income subject to federal tax)
Box 2
Federal income tax withheld
Box 3
Social Security wages
Box 4
Social Security tax withheld
Box 5
Medicare wages
Box 6
Medicare tax withheld
W-2 includes details like Social Security and Medicare wages, allocated tips, social security tips, and cash wages. Pre-tax deductions such as 401(k) contributions or health savings account contributions reduce the amount in Box 1 but may not reduce Box 3 or Box 5.
Employers must furnish W-2s to employees and file them with the Social Security Administration by January 31 following the tax year. For 2025 wages, that deadline is January 31, 2026.

Employers issue W-2s; individual taxpayers file Form 1040. Both forms must reconcile for proper income reporting.
Any worker classified as an employee under IRS common-law rules receives a Form W-2. A statutory employee also receives a W-2, though with a specific checkbox marked. Independent contractors and freelancers receive Form 1099-NEC instead, reporting non-employee compensation rather than wages. The distinction matters: employees have payroll taxes (Social Security and Medicare tax) split between employer and employee, while self-employed individuals pay the full amount via Schedule SE.
Nearly all U.S. employees who receive a W-2 and meet income thresholds must file a Form 1040. Even those with low total income may benefit from filing to claim a tax refund of withheld taxes or refundable tax credits. Self-employed taxpayers do not receive W-2s for their own business income; they report profit or loss on Schedule C and pay self-employment tax separately.
Misclassification (receiving a 1099 when the working relationship is actually employment) has real consequences: the worker loses employer-paid Social Security and Medicare contributions, and the employer faces potential penalties. VJM Global – USA can help employers review their worker classification policies, payroll processes, and sales tax compliance obligations to avoid these issues.
Here is the core difference between 1040 and W-2, broken down side by side:
Feature
Form 1040
Form W-2
What it is
Your actual tax return
An income reporting document
Who prepares it
The taxpayer (or their certified public accountant)
The employer
Filed with
IRS
SSA, IRS, state authorities
Purpose
Compute total tax liability, refund, or balance due
Report annual wages and taxes withheld by employers
Income covered
All income types (wages, business income, investment income, additional income)
Only wages from that specific employer
When due
April 15 (tax year 2025: April 15, 2026)
January 31 (tax year 2025: January 31, 2026)
Some taxpayers mistakenly treat a W-2 as their tax return. The W-2 is just one form; it feeds into the 1040, which is where tax benefits, deductions, and credits are applied. You do not file Form W-2 to calculate your tax. The W-2 is essential for completing Form 1040 during tax filing, but it is not a substitute for the return itself.
Mismatches between W-2 data and the Form 1040 filed can trigger an IRS notice or CP2000 underreporter letter, where the IRS proposes additional tax based on information they already have on file.
A correct Form 1040 pulls wage and withholding figures directly from each Form W-2. You must gather all W-2s and any applicable 1099s when preparing your tax return.
Box 1 of W-2 shows total wages, tips, and other compensation. The amounts from all your W-2s combine into the wages line on Form 1040. Federal income tax withheld (Box 2) from all W-2s flows into the payments section of Form 1040, reducing your total tax or increasing your refund.
Example: An employee with two W-2s from two employers; Job A reports $50,000 in wages with $6,000 federal tax withheld, Job B reports $30,000 with $3,000 withheld. On Form 1040: total income from wages is $80,000, and total federal taxes withheld is $9,000. Those $9,000 reduce whatever the computed tax turns out to be. If the computed tax is $7,500, the taxpayer gets a $1,500 tax refund.
If an employer sends a W-2 with an incorrect SSN or wrong address, a corrected W-2 (Form W-2c) must be issued. If you already filed your 1040, you may need to amend it using Form 1040-X. Social Security and Medicare tax figures from Boxes 4 and 6 do not reduce your federal income tax directly but feed your earnings record at the Social Security Administration for retirement and disability benefit calculations.
The deadlines differ because the tax forms serve different roles.
Event
Deadline
Notes
Employer sends Form W-2 to employees and SSA
January 31
For tax year 2025: January 31, 2026
Individual files Form 1040
April 15
For tax year 2025: April 15, 2026
Extension deadline (Form 4868)
October 15
Payment still due by April 15
Employers filing 10 or more W-2s must file electronically with the SSA unless granted a waiver. Penalties for late or incorrect W-2s range from $60 per form (filed within 30 days late) to $330 or more per form (filed after August 1 or not corrected). Intentional disregard carries a minimum $690 per form with no cap.
For individuals, late Form 1040 filing triggers a failure-to-file penalty, and unpaid taxes accrue a separate failure-to-pay penalty plus interest, situations where professional IRS tax resolution and audit support can be critical.
A large share of IRS notices stem from basic 1040 vs W-2 errors rather than complex tax planning issues. Common mistakes include:
These mismatches result in CP2000 letters proposing how much tax you additionally owe. Taxpayers should respond promptly, compare the notice against their W-2s and filed 1040, and consider professional help if they disagree.
VJM Global – USA regularly assists both employees and employers in resolving wage and withholding mismatches, amended returns, and penalty abatement requests as part of its broader professional tax resolution services for USA businesses.
While the W-2 form itself does not list deductions or credits, the wages and taxes on your W-2 feed directly into eligibility tests on Form 1040. The earned income credit for tax year 2025 reaches a maximum of $8,046 for taxpayers with three or more qualifying children, with AGI phase-out ending around $61,555 for single or head-of-household filers. The child tax credit for 2025 is $2,200 per qualifying child, with a refundable portion (Additional Child Tax Credit) up to $1,700.
Employees with side businesses report W-2 wages on Form 1040 and business income or loss on Schedule C. They pay self-employment tax via Schedule SE on top of any Social Security and Medicare withholding from their W-2. Workers contributing to employer retirement plans see lower taxable income in Box 1, which affects their total tax liability and possible refund.
Example: A taxpayer with $35,000 in W-2 wages and one qualifying child could claim both the child tax credit and the earned income credit on Form 1040. The earned income credit alone could be worth up to $4,328 for one qualifying child, directly reducing what they owe or increasing their refund.
VJM Global – USA has experienced CPAs, Enrolled Agents, and tax professionals supporting both individuals and employers on U.S. tax compliance, including tax preparation outsourcing services in India for USA CPA firms. We've seen firsthand how small W-2 errors cascade into amended returns and penalty notices.
For individual taxpayers, we prepare and review Form 1040 and related schedules (Schedule C, Schedule EIC, and others), reconcile W-2 and 1099 information to reduce IRS mismatch risk, and advise on credits including the earned income credit, child tax credit, and education benefits, often through our expert U.S. tax return preparation outsourcing services.
For employers, we advise on correct worker classification for W-2 vs 1099, coordinate with payroll systems (QuickBooks, Sage, NetSuite) to make sure W-2 filings are accurate and timely, and assist with IRS and Social Security Administration corrections when errors surface, alongside expert tax preparation services for LLCs and LLPs in the USA.
For cross-border employees and foreign-owned U.S. entities, we advise on how W-2 wages, Form 1040 or 1040-NR filings, and international tax rules interact, drawing on our broader global tax, accounting, and business consulting services. If you manage multiple W-2s, stock compensation, or a growing workforce, reach out to our team at [email protected].
Yes. If your gross income exceeds IRS filing thresholds for your filing status and age in that tax year, you must file Form 1040 regardless of withholding. Filing also lets you claim a tax refund if your employer withheld more than your total tax, or if you qualify for refundable credits not reflected on the W-2. Some very low-income taxpayers are not required to file but may choose to do so to recover withheld taxes.
Employers must provide Form W-2 by January 31. If it hasn't arrived by mid-February, contact your employer's payroll or HR department first. If that fails and you still lack the W-2 by late February, call the IRS at 800-829-1040. You can eventually use Form 4852 (Substitute for W-2) to file taxes. Keep your final pay stub for the tax year; it helps reconstruct wages and taxes withheld.
The IRS recommends keeping copies of your tax returns and W-2s for at least three years after the filing date or due date, whichever is later. If you underreported income by more than 25%, the IRS can look back six years. Store digital copies in a secure location so you can respond quickly to any future IRS notice.
You should not. Filing without all W-2s causes mismatches with IRS records and often leads to amended return filings via Form 1040-X. If you worked for multiple employers, wait for each W-2 to arrive. If a W-2 is delayed, resolve the delay rather than rushing an inaccurate return.
The Social Security Administration uses your W-2 wage records (specifically Box 3, Social Security wages, up to the annual wage base) to calculate retirement, disability, and survivor benefits. Underreported or missing W-2 wages reduce your lifetime earnings record and can lower your eventual benefit amount. Check your Social Security statement periodically at ssa.gov to confirm your reported earnings match your W-2 history.
{"@context":"https://schema.org","@type":"FAQPage","mainEntity":[{"@type":"Question","name":"Do I still need to file a Form 1040 if all my tax was withheld on my W-2?","acceptedAnswer":{"@type":"Answer","text":"Yes. If your gross income exceeds IRS filing thresholds for your filing status and age in that tax year, you must file Form 1040 regardless of withholding. Filing also lets you claim a tax refund if your employer withheld more than your total tax, or if you qualify for refundable credits not reflected on the W-2. Some very low-income taxpayers are not required to file but may choose to do so to recover withheld taxes."}},{"@type":"Question","name":"What if my employer hasn't sent my W-2 by early February?","acceptedAnswer":{"@type":"Answer","text":"Employers must provide Form W-2 by January 31. If it hasn't arrived by mid-February, contact your employer's payroll or HR department first. If that fails and you still lack the W-2 by late February, call the IRS at 800-829-1040. You can eventually use Form 4852 (Substitute for W-2) to file taxes. Keep your final pay stub for the tax year; it helps reconstruct wages and taxes withheld."}},{"@type":"Question","name":"How long should I keep my 1040 and W-2 forms?","acceptedAnswer":{"@type":"Answer","text":"The IRS recommends keeping copies of your tax returns and W-2s for at least three years after the filing date or due date, whichever is later. If you underreported income by more than 25%, the IRS can look back six years. Store digital copies in a secure location so you can respond quickly to any future IRS notice."}},{"@type":"Question","name":"Can I file my Form 1040 before I receive all my W-2s?","acceptedAnswer":{"@type":"Answer","text":"You should not. Filing without all W-2s causes mismatches with IRS records and often leads to amended return filings via Form 1040-X. If you worked for multiple employers, wait for each W-2 to arrive. If a W-2 is delayed, resolve the delay rather than rushing an inaccurate return."}},{"@type":"Question","name":"How do W-2 wages affect my Social Security benefits in the future?","acceptedAnswer":{"@type":"Answer","text":"The Social Security Administration uses your W-2 wage records (specifically Box 3, Social Security wages, up to the annual wage base) to calculate retirement, disability, and survivor benefits. Underreported or missing W-2 wages reduce your lifetime earnings record and can lower your eventual benefit amount. Check your Social Security statement periodically at ssa.gov to confirm your reported earnings match your W-2 history."}}]}